Close Menu
    Facebook X (Twitter) Instagram
    TRENDING :
    • The loneliness economy is building tech for the average customer, but that customer doesn’t exist
    • Opetaia Out of Wilder Fight With Hand Injury
    • ‘Millennials need to retire,’ say frustrated Gen Z job seekers on TikTok
    • Roseanne Barr Helps Grandson Come Out on Podcast
    • Replit’s CEO on its stunning turnaround, ‘AI psychosis,’ and the risk Silicon Valley is ignoring
    • Rookie Chris Cenac Jr. Gets Extended Minutes for Celtics vs. Magic
    • 4 places where cutting AI costs is a mistake
    • Inside the Clippers’ Super Bowl Video and the Art of Clipping
    Populist Bulletin
    • Home
    • US Politics
    • World Politics
    • Economy
    • Business
    • Headline News
    Populist Bulletin
    Home»Business»Average U.S. mortgage rate rises to 7.28%—the highest level in nearly three years
    Business 3 Mins Read

    Average U.S. mortgage rate rises to 7.28%—the highest level in nearly three years

    Business 3 Mins Read
    Share Facebook Twitter Pinterest LinkedIn Tumblr Telegram Email Copy Link
    Follow Us
    Google News Flipboard
    Share
    Facebook Twitter LinkedIn Pinterest Email

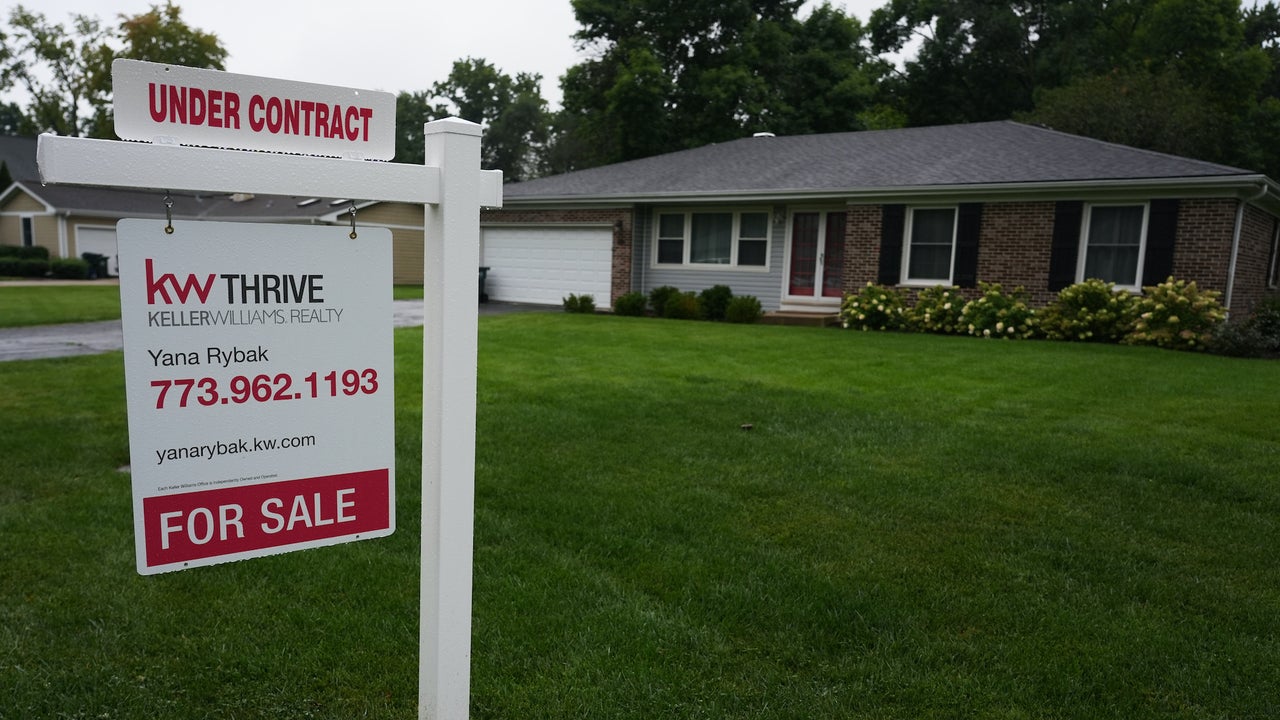
    The average long-term U.S. mortgage rate jumped this week to its highest level in nearly three years.

    The benchmark 30-year fixed-rate mortgage rose to 7.28% from 7.03% last week, mortgage buyer Freddie Mac said Thursday, the biggest leap in several years. A year ago, the average rate was 6.34%.

    It is the sixth consecutive week that mortgage rates have increased.

    The average rate is now the highest it’s been since Nov. 22, 2023, when it reached 7.29%.

    Borrowing costs on 15-year fixed-rate mortgages, often sought by borrowers refinancing a home loan, also climbed this week. That average rate increased to 6.60% from 6.42% last week. A year ago, it was at 5.55%.

    Higher mortgage rates can add hundreds of dollars a month to borrowers’ costs, limiting homebuyers’ purchasing power. As rates rise, that can also lead prospective home shoppers to delay buying.

    In late February, the average rate on a 30-year mortgage briefly dipped to 5.98%, its lowest level going back to late 2022. The roughly 1 percentage point increase in the rate since then translates roughly into an additional $276 a month cost for a borrower financing a $400,000 home loan at the current average rate.

    Depending on a borrower’s income, credit, and other factors, they may qualify for a rate on a 30-year mortgage that is below or above the current average.

    The housing market has been stuck in a rut this year in large part because of elevated mortgage rates, which have been climbing in the months since the U.S. and Israel attacked Iran in late February.

    Mortgage rates are influenced by inflation, Federal Reserve policy and bond-market investors’ expectations for the economy, among other factors. They generally follow the trajectory of the 10-year Treasury yield, which lenders use as a guide to pricing home loans.

    Expectations of higher inflation amid surging oil prices have pushed up the 10-year Treasury yield, which was at 3.97% in late February, before the war began. It surged to 5.27% in midday trading on the bond market Thursday. That puts it roughly back to where it was in 2007, on the eve of the real estate-induced financial crisis.

    High yields slow the overall economy by making it more expensive for everyone to borrow money, while undercutting prices for stocks and other investments.

    The U.S. housing market has been in a slump since 2022, when mortgage rates began to climb from pandemic-era lows. Sales of previously occupied U.S. homes were essentially flat last year, stuck at a 30-year low.

    Last month the National Association of Realtors said that existing home sales fell 2% in August from July to a seasonally adjusted annual rate of 3.98 million units. That was their slowest annual pace in more than a year.

    And many potential homeowners are now hitting the brakes.

    Mortgage applications, which include loans to buy a home or refinance an existing mortgage, tumbled 6% last week from the previous week, according to the Mortgage Bankers Association. This marks the fourth straight weekly drop.

    Applications for loans to refinance existing mortgages also declined.

    The elevated mortgage rates are driving more prospective homebuyers to adjustable-rate mortgages, or ARMs. Such loans, which typically offer lower initial interest rates than traditional 30-year, fixed-rate mortgages, accounted for more than 10% of all mortgage applications last week, MBA said.

    —Michelle Chapman, AP business writer


    Source link

    Share. Facebook Twitter Pinterest LinkedIn Tumblr Email

    Related Posts

    The loneliness economy is building tech for the average customer, but that customer doesn’t exist

    November 19, 2026

    ‘Millennials need to retire,’ say frustrated Gen Z job seekers on TikTok

    November 19, 2026

    Replit’s CEO on its stunning turnaround, ‘AI psychosis,’ and the risk Silicon Valley is ignoring

    November 19, 2026
    Top News
    Business 6 Mins Read

    How Trump is trying to convince skeptical voters that he can deliver on affordability

    Business 6 Mins Read

    President Donald Trump is adjusting his messaging strategy to win over voters who are worried…

    7 Simple Steps to Register a DBA Under Your LLC

    February 1, 2026

    Week 9 Power Rankings: PAC and WCAL Titles Up for Grabs

    October 20, 2026

    Who’s Afraid of the Epstein Files?

    November 18, 2025
    Top Trending
    Business 8 Mins Read

    The loneliness economy is building tech for the average customer, but that customer doesn’t exist

    Business 8 Mins Read

    Investors have poured money into startups promising to solve our loneliness epidemic.…

    World Politics 1 Min Read

    Opetaia Out of Wilder Fight With Hand Injury

    World Politics 1 Min Read

    Australian cruiserweight Jai Opetaia has withdrawn from his December 11 heavyweight debut…

    Business 3 Mins Read

    ‘Millennials need to retire,’ say frustrated Gen Z job seekers on TikTok

    Business 3 Mins Read

    Millennials need to retire. That’s the sentiment in certain corners of TikTok,…

    Categories
    • Business
    • Economy
    • Headline News
    • Top News
    • US Politics
    • World Politics
    About us

    The Populist Bulletin was founded with a fervent commitment to inform, inspire, empower and spark meaningful conversations about the economy, business, politics, government accountability, globalization, and the preservation of American cultural heritage.

    We are devoted to delivering straightforward, unfiltered, compelling, relatable stories that resonate with the majority of the American public, while boldly challenging false mainstream narratives that seem to only serve entrenched elitists, and foreign interests.

    Top Picks

    The loneliness economy is building tech for the average customer, but that customer doesn’t exist

    November 19, 2026

    Opetaia Out of Wilder Fight With Hand Injury

    November 19, 2026

    ‘Millennials need to retire,’ say frustrated Gen Z job seekers on TikTok

    November 19, 2026
    Categories
    • Business
    • Economy
    • Headline News
    • Top News
    • US Politics
    • World Politics
    Copyright © 2025 Populist Bulletin. All Rights Reserved.

    Type above and press Enter to search. Press Esc to cancel.